

Nelson Mandela famously said that “education is the most powerful weapon which you can use to change the world.” For many families, investing in a child’s education is a central financial planning goal, but the cost of doing so has grown rapidly. For this reason, grandparents often like the idea of helping fund a portion of their grandchildren’s education, especially because it creates a legacy that lasts longer than traditional gifts.
Historically, grandparents have had to navigate specific rules when gifting to grandchildren to prevent unintended financial consequences, including tax and financial aid considerations. However, recent changes to federal financial aid now exclude grandparent-owned 529 accounts from the student assets section of the aid calculation. This removes a drawback of these accounts that was a problem historically. This change makes them worth another look as part of a family’s broader financial plan for education funding.
The rising cost of a college education
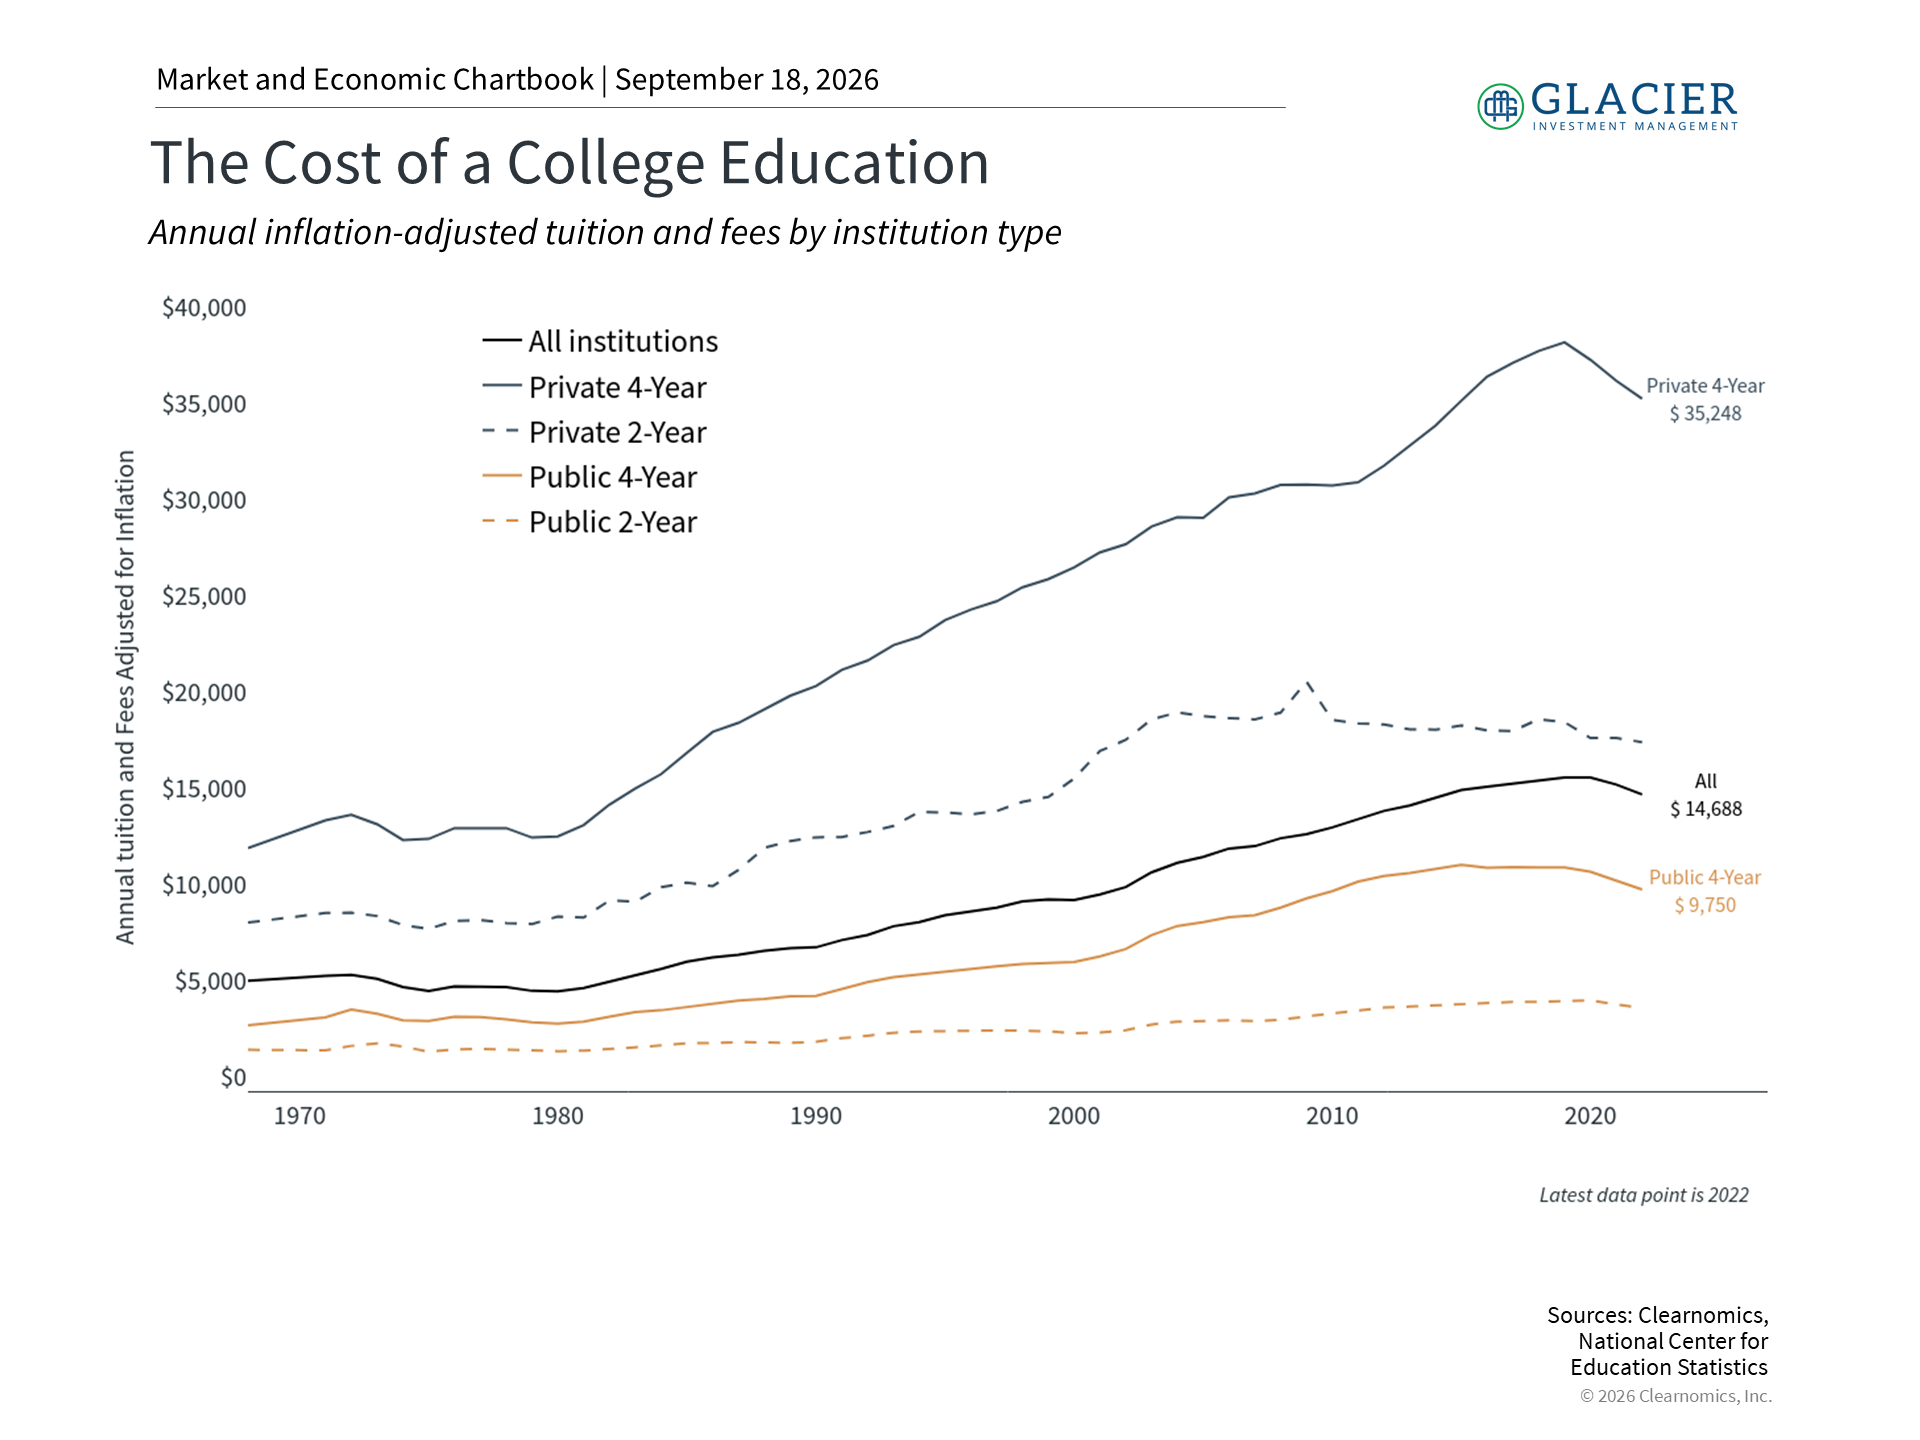
Attending college is a reason to celebrate but also represents a major source of financial stress for many families. The cost of obtaining a college education can be significant and has easily outpaced inflation over the past 40 years. The accompanying chart shows the average level of tuition and fees after adjusting for inflation, according to the National Center for Education Statistics, since 1963. It’s easy to see that these costs have grown rapidly, especially for private 4-year institutions.
Tuition and fees alone represent only one part of these expenses, with families also responsible for housing, food, books, transportation and other education-related expenses which now average over $17,000 a year according to the College Board.1 These figures underscore what most families already know: the importance of planning and saving early.
To manage these costs, it’s common for families to combine different sources of funds, including parent and student income and savings, scholarships and grants, loans, and in some cases, financial support from relatives and friends. This is where grandparent-owned 529 accounts can be beneficial.
Although parents often open 529 accounts for their children, grandparents can open accounts for their grandchildren as well. Previously, this strategy was not always advantageous because distributions from a grandparent-owned 529 plan used to help pay for a grandchild’s college expenses were reported on the FAFSA form as student income.2
A recent change to recognition of student assets has changed this calculation. For example, under the previous rules, student income, a component of the Student Aid Index (SAI), was included at a rate of 50%. Distributions from grandparent-owned 529 accounts were included in this component.3 While not the only means for a grandparent to contribute to a student's education, grandparent-owned 529 accounts are now exempt from this treatment.
Higher education can support a lasting legacy
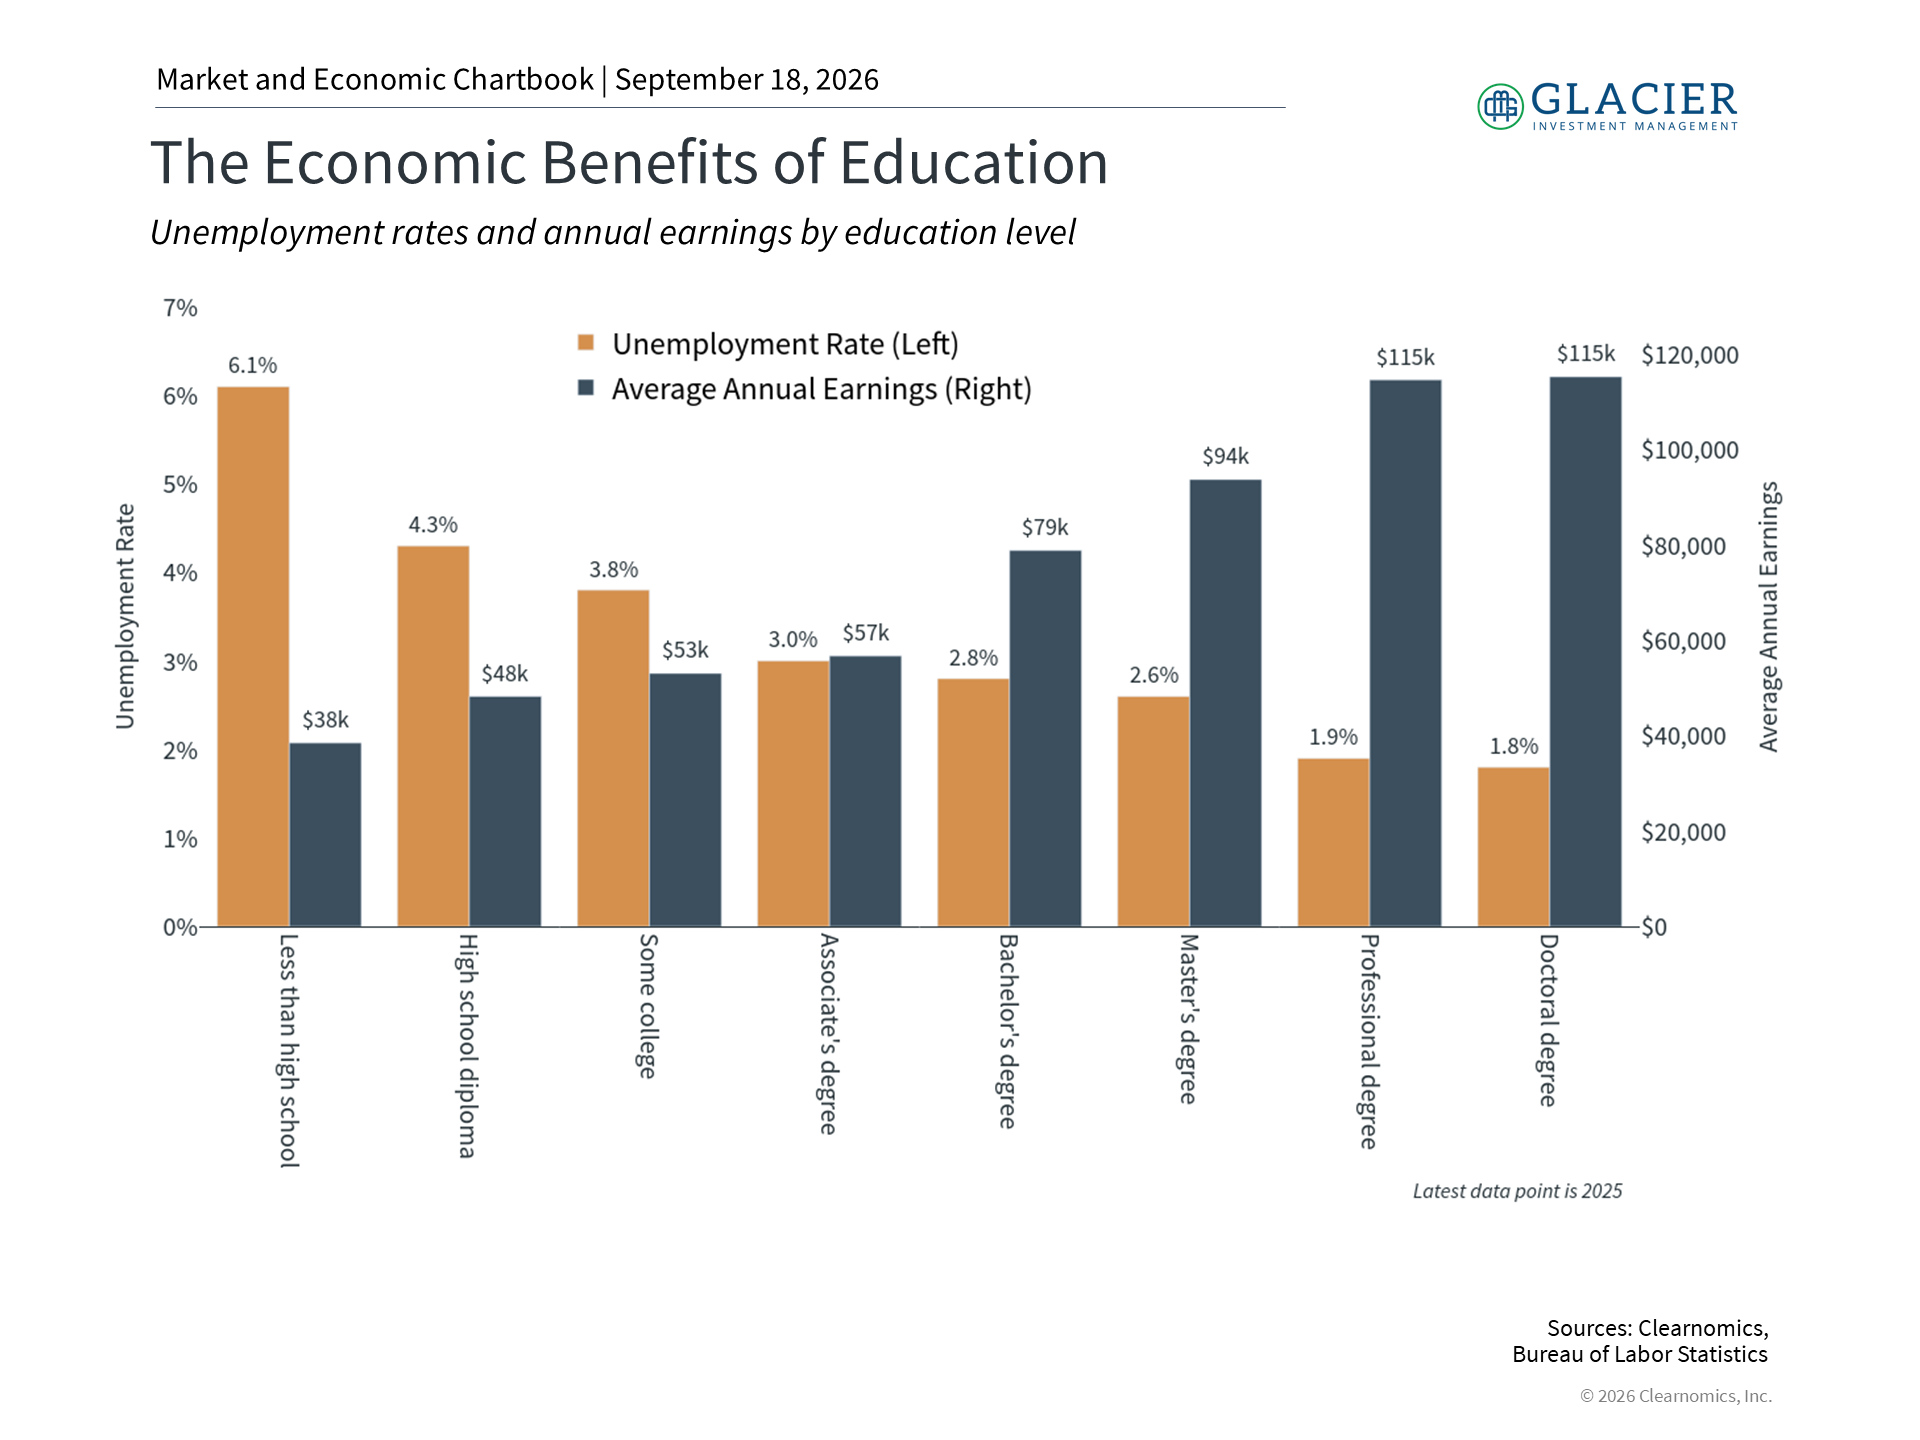
Despite rising costs, the latest figures from the Bureau of Labor Statistics show that the returns to education over a lifetime are still strong. Not only are average earnings higher for each additional level of education, but unemployment rates are lower as well. For those with a high school diploma who did not attend college, for instance, the unemployment rate is 4.3%, just around the national average. However, those with a bachelor’s degree experience an average jobless rate of 2.8%, and for those with professional degrees or a doctorate, this rate is under 2%.4 So, setting up grandchildren for future success is one reason why funding education is a great way to create a lasting legacy.
A benefit of grandparent-owned 529 accounts is that the account owner retains control over the assets, including when distributions are made and whether the beneficiary needs to be changed to another qualifying family member, or even the account owner. Having that flexibility is key because education plans can change. For instance, a grandchild may receive a scholarship, attend a less expensive school, or decide to not continue college. In those cases, families have several options for unused funds.
The SECURE 2.0 Act, for example, allows up to $35,000 to be transferred from a 529 account into the grandchild’s Roth IRA over their lifetime tax-free and penalty-free, provided certain conditions are met.5 Specifically, the savings account must have been open under the grandchild’s name for at least 15 years. However, under this scenario, annual Roth IRA contribution limits and earned income requirements still apply.
Another option is using up to $10,000 to pay off qualified federal or private student loans. This can include the primary beneficiary or their siblings.6 Also, starting in 2026, grandparents can now withdraw up to $20,000 tax-free per grandchild for annual K-12 tuition.
529 accounts have state-specific aggregate lifetime contribution limits. However, they do not have an annual contribution cap making them attractive for estate planning and gifting. Still, limits exist for tax-free gifting and overall aggregate account balances set by each state. For 2026, a grandparent can gift up to $19,000 each year per grandchild without triggering federal gift tax reporting.7
A grandparent who wants to make a larger contribution can front-load up to five years of gifts into a single contribution which translates to up to $95,000.8 A major advantage here is that it gives the assets more time to compound tax-free.
Depending on where they live, grandparents may receive an additional benefit.9 More than 30 states offer an income tax deduction or credit for certain 529 contributions. In most cases, the tax-benefit is tied to using the taxpayer’s home-state plan, while nine states offer “tax parity” which grants benefits for contributions to any state’s plan.
Taken together, 529 accounts can be a great tool for financial planning, if used thoughtfully. This is especially relevant since a growing number of families are looking for tax-efficient ways to help cover the costs of their children’s college education and reduce the need for student loans. Grandparents can play an important role in that effort, and 529 plans provide a tax-advantaged way to do so. Of course, while supporting a grandchild’s college education is a generous gift, contributions should be balanced against a grandparent’s own retirement needs and long-term financial goals.
The Bottom Line
Grandparents can leave a lasting legacy for their grandchildren in many different ways, including grandparent-owned 529 accounts. With careful planning, they can strategically invest in their grandchildren’s future by helping with education costs using tax-efficient strategies.
References
1. https://research.collegeboard.org/media/pdf/Trends-in-College-Pricing-and-Student-Aid-2025-final_1.pdf
2. https://www.congress.gov/crs-product/R46909
3. https://www.congress.gov/crs-product/R48835
4. https://www.bls.gov/emp/
5. https://www.congress.gov/crs_external_products/R/HTML/R42807.html
6. https://www.irs.gov/taxtopics/tc313
7. https://www.irs.gov/faqs/interest-dividends-other-types-of-income/gifts-inheritances/gifts-inheritances-1
8. https://www.irs.gov/forms-pubs/about-form-709
9. https://www.irs.gov/newsroom/tax-benefits-for-education-information-center